"He explains his findings in a clear and concise manner that clients find very helpful. His track record of work for HMRC is also of great value."
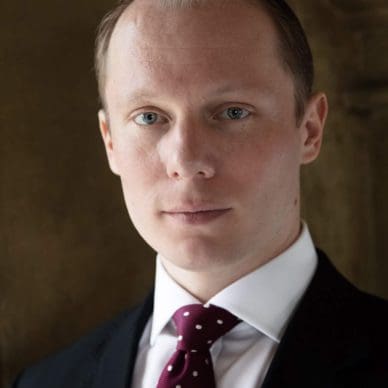
Patrick Boch practices in all areas of tax law, as well as chancery, insolvency and commercial (including arbitration). He appears regularly in the Courts and Tribunals, and is an experienced advocate.
He has particular expertise in relation to tax issues in civil litigation, such as claims in mistake, professional negligence, contractual disputes and settlements.
He also has considerable experience in tax avoidance disputes, such as those involving the GAAR, being a former member of HMRC’s Solicitor’s Office.
In his advisory practice, he has a particular interest in pensions taxation. However, he regularly advises on a broad variety of private client tax matters.
He is a Chartered Tax Adviser, holding the Avery Jones Medal for the highest result in his application paper; and an Indian Advocate with a particular interest in India-related arbitration.
He is fluent in Polish, Danish and Hindi.
Tax litigation
Patrick Boch has extensive tax litigation experience. His recent cases include:
- COMFG Holdings v Welsh Revenue Authority [2026] UKFTT 237 (strike out application on behalf of WRA – whether pension trustees were also acting as partners while the renting out of a commercial property – application allowed.)
- Janet Bray Ltd [2025] SFTD 637 (discovery assessment – whether a director or her advisers were careless when implementing a scheme involving a long-term loan from an EBT – whether the carelessness caused the PAYE loss assessed – appeal dismissed – on appeal to the Upper Tribunal)
- Landmaster Investment Ltd [2024] SFTD 139(application of options and rights of pre-emption to SDLT definition of “residential property”) (see also The How Development Ltd [2023] UKUT 84)
- Shinelock Ltd [2023] STC 976 (Upper Tribunal) (whether the loan relationship code and distribution rules applied to render certain payments by a company taxable – whether the FTT had jurisdiction to hear certain arguments)
- Thursford Enterprises [2022] UKFTT 240 (whether the Thursford Christmas Spectacular was eligible for theatre tax relief, being an “other dramatic piece” – whether the performers were wholly or mainly playing “roles” – appeal allowed)
Ongoing cases include:
- a pensions tax dispute (whether regulations made under s.268 FA 2004 are ultra vires)
- a dispute as to whether joint liability notices (Sch 13 to FA 2020) rendering a taxpayer personally liable for company tax debts are valid
- whether juice ‘shots’ are ‘beverages’ for VAT purposes
- a High Court claim for the rectification of a trust deed in connection with a dispute concerning the availability of incorporation relief (s.162 TCGA)
- whether HMRC must account for a refund made further to an avoidance scheme, but to a third party who procured it by fraud
He has also acted as an expert witness in a commercial dispute before a Polish court on whether raw tobacco was subject to customs duty in the United Kingdom and whether HMRC’s seizure of those goods had been lawful.
Civil litigation and arbitration
Patrick Boch is regularly instructed in civil disputes. Recent cases include:
- Google LLC v Robertson [2026] 1 WLR 1225 (Court of Appeal) (whether the English courts had power under CPR 6.34(2)(b) to regularise service of a claim form where form N510 had been served late – whether the costs award at first instance amounted to an error of law – submissions noted as “careful” – dispute at first instance included successfully establishing that the English courts had jurisdiction to hear Mr Robertson’s Equality Act claim pursuant to a contractual jurisdiction clause)
- Abcor Finance v Binomia [2025] EWHC 2374 (High Court) (whether under a set of complex financial agreements the alleged debt was due and payable – whether the Court should exercise its discretion to make a winding up order – petition dismissed)
- The Danish cum/ex dividend withholding tax case litigation (£1.2bn claim bought by Danish tax authority – whether applications for withholding tax refunds amounted to misrepresentations – assisted with case on ‘reasonable reliance’ and other issues arising from 4,000 pages of Danish language documents – claim dismissed in Skatteforvaltningen v Solo Capital Partners & Ors [2025] EWHC 2364)
- M & S v E (2025) (arbitration under the Chartered Institute of Arbitrators’ BAS Rules – whether a US fertility agency, which had arranged commercial surrogacy services for the claimants, was liable to damages in unjust enrichment in spite of procuring the birth of a daughter – whether the contract was unlawful or void ab initio on account of commercial surrogacy being prohibited under English law)
Examples of matters not concluded at trial/reported:
- Probate disputes. Recent examples: (a) a successful application in the High Court to strike out a claim for lack of standing by the claimant; and (b) settlement by mediation of a claim brought in proprietary estoppel. Routinely deals with capacity issues (including expert witnesses), disputes between executors, and construction of Wills.
- Professional negligence claims. Advised on a potential claim against a major US law firm arising from alleged negligence in a treaty arbitration. Routinely advises on potential claims against tax advisors.
- Insolvency disputes. Instructed in a complex £10m petition involving inter alia a challenge to the jurisdiction of the English courts. Routinely deals with HMRC-led petitions.
- Commercial & Arbitration. Was counsel in a claim under the LCIA rules of arbitration between a US company and a large Russian conglomerate as to whether the US company was entitled to liquidated damages of $4m upon termination. Instructed as junior counsel in a complex High Court dispute arising from an agreement to divide the family business between two brothers and their sons.
Advisory practice
Patrick Boch regularly advises on tax matters, most commonly within the private client sphere. Recent examples include:
Pension taxation
- Whether a scheme worth £10m was (definitionally) a QNUPS or an EFURBS, and whether it would be effected by the new s.150A IHTA 1984 (whereby pension schemes are to be subject to IHT in addition to income tax).
- Whether either of two versions of an arrangement enabling investment of pension funds into a connected company was effective, such as not to result in unauthorised payment charges or scheme sanction charges.
Litigation/settlement context
- Advice on whether, in a proposed settlement of a £50m proprietary estoppel claim, IHT could be avoided by use of a deed of variation.
- Instructed as junior counsel to advise on the tax treatment damages payable under a settlement in a £20m wrongful birth case.
- HMRC’s ability to demand payment of tax in circumstances where a taxpayer had made a payment to the Scottish Ministers on settlement of a Proceeds of Crime Act claim alleging tax evasion.
- Whether HMRC could enforce a demand for payment pursuant to a solicitor’s undertaking on the basis the undertaking created a third party right.
Capital/structuring/transactional
- The availability of Incorporation Relief (s.165 TCGA) in property business cases.
- Whether (a) UK withholding tax was to be deducted on interest payments made by a foreign company, owning a £50m UK property, to a foreign lender; (b) the tax position would change upon the company’s business being placed in a Jersey trust; and (c) a variation of the loan agreement would be caught by inter alia the unallowable purpose rules (s.441, CTA 2009).
- The restructuring of an overseas property portfolio held by multiple companies (s.136 TCGA, etc).
- Valuation, for IHT purposes, of shares in a £100m Indian company, including the UK tax effects of a shareholders’ agreement governed by Indian law.
- The UK tax treatment of German ‘conditional gifts’ by a father to his daughter.
- Whether the appreciation of an asset provided in connection with a loan represented capital or income.
Creative tax reliefs
- Whether under a contractual provision it was “reasonable” for a production company to appeal a refusal of theatre tax relief by HMRC.
- Whether an Indian film shot (largely) in London was eligible for film tax.
Value Added Tax:
- The VAT treatment of erotic chat room services provided through a multi-national structure.
- Whether certain Botox treatments were medical or cosmetic for VAT purposes.
Other/General
- Traders in financial instruments (whether trading or investing).
- The statutory residence test.
- Whether a purchase of a client’s shares under a litigation settlement was to be taxed under the employment related securities regime.
- UK tax treatment of overseas life assurance policies.
- Whether a TV presenter was self-employed, or an employee, for tax purposes.
- The correct classification of a banking client under CRS.
He has also advised the UK government on Indian law issues in connection with the negotiation of a treaty.
- COMFG Holdings Ltd v WRA [2026] UKFTT 237
- Robertson v Google LLC [2026] 1 WLR 1225 (Court of Appeal)
- Abacor Finance Securities Ltd v Binomia Ltd [2025] EWHC 2374
- Janet Bray Ltd v HMRC [2025] SFTD 637
- Kane and White v HMRC [2023] UKFTT 866
- Shinelock Ltd v HMRC [2023] STC 976 (Upper Tribunal)
- The How Development Ltd v HMRC [2023] UKUT 84
- Thursford Enterprises Limited v HMRC [2022] UKFTT 240
- Landmaster Investment Ltd v HMRC [2024] SFTD 139
- Cork Bonded Warehouse Limited v HMRC [2022] UKFTT 215
- Shinelock Ltd v HMRC [2021] UKFTT 320
- Shinelock Ltd v HMRC [2021] UKFTT 318
- The How Development 1 Ltd v HMRC [2021] UKFTT 248
- Gill v HMRC [2018] UKFTT 245
- Winstanley v HMRC [2018] UKFTT 154
- Gill v HMRC [2017] UKFTT 597
- Badzyan v HMRC [2017] UKFTT 439
- Archer v HMRC [2016] UKFTT 141
"He explains his findings in a clear and concise manner that clients find very helpful. His track record of work for HMRC is also of great value."
- LTN Tax Conference - 08/09/2026
- Skatteforvaltningen v Solo Capital Partners & ors [2025] EWHC 2364 (Comm).
- Citywealth Future Leaders Awards 2025
- Legal Directory 2024 Bar Rankings
- Upper Tribunal decision - Shinelock Ltd v HMRC
- Chambers and Partners UK Bar Awards 2022
- Judgement – RE: Thursford Enterprises
- Judgement – RE: Thursford Enterprises
- Patrick Boch and Ross Birkbeck appointed to C Panel
- Successful costs application against HMRC
- Congratulations to Patrick Boch on the Avery Jones Medal
- Patrick Boch Recently Acted as an Expert Witness
- Old Square Tax Chambers ranked as a leading set
- Revenue Powers
- Free Seminar: Taxation of Trusts
- Liability of Non-UK Residents to Income Tax and Capital Gains Tax and use of UK Double Taxation Conventions by non-UK residents and UK-Residents
- Settling Disguised Remuneration Enquiries - where we are in 2025
- Autumn VAT Round-Up
- KEY HAVEN PUBLICATIONS LTD - 42nd Annual Oxford Four-Silk, Fourteen-Speaker Residential Seminar - PRACTICAL TAX PLANNING 2024
- Key Haven 2024 - PRACTICAL TAX PLANNING 2023
- UK Property Taxation: What You Need to Know Now
- Taxation of Trusts
- Revenue Powers
- HMRC’s attack on Tax Avoidance
- Key Haven Publications 2022 – 40th Annual Oxford Four-Silk Sixteen-Speaker
- Key Haven Publications 2021 – 39th Annual Oxford Four-Silk Fourteen-Speaker Residential Seminar
- Key Haven Tax Planning Webinar
- KEY HAVEN PUBLICATIONS LTD – PRACTICAL TAX PLANNING 2019
- LL.B. (Hons) Law, University of Buckingham (2007)
- Cand. jur. (LL.M.), University of Copenhagen (2015)
- Fluent: Danish, Polish and Hindi
- Intermediate: Spanish and German
- Revenue Bar Association
- Chancery Bar Association
- The Attorney General’s C Panel of Junior Counsel to the Crown
Patrick Boch is regulated by the Bar Standards Board